MZTI vs SFM: Two Cheap Consumer Stocks, Two Very Different Bets
MZTI and SFM are both trading below historical valuations, but their investment cases are very different. MZTI is betting on Bachan’s and margin expansion, while SFM is relying on new-store growth despite weak comparable sales.
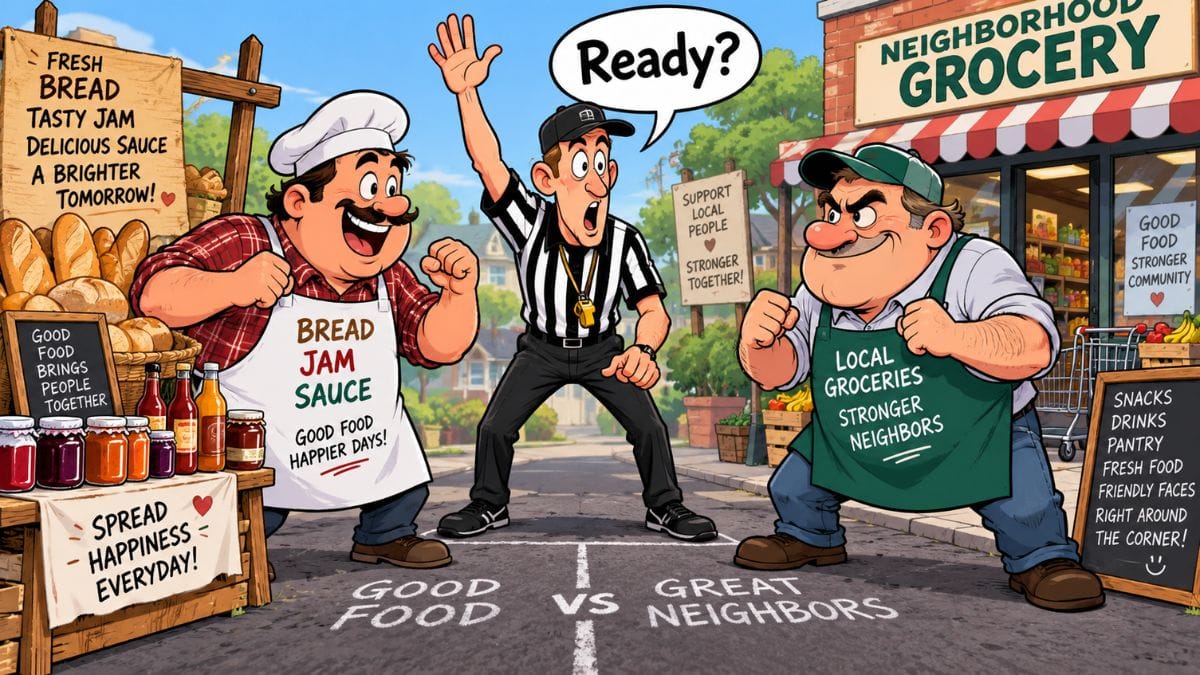
Mikirduit — Two beaten-down consumer-staples stocks are offering investors very different kinds of bargains.
3 Key Takeaways
- MZTI offers the wider valuation cushion, with a 14.5x P/E, roughly 51% upside to its DCF estimate, and a dividend yield of about 4.1%, but the thesis depends heavily on Bachan’s offsetting weakness in the legacy business.
- SFM has the clearer structural-growth runway through aggressive store expansion, private-label growth and e-commerce, but comparable-store sales remain weak and higher revenue is not yet translating into higher operating profit.
- The key difference is margin of safety: MZTI carries more execution risk but more potential rerating upside, while SFM offers stronger long-term expansion visibility at a valuation that sits much closer to estimated fair value.
The Marzetti Company (NASDAQ: MZTI) is betting that its acquisition of Bachan’s can revive growth while a long-running margin-improvement program lifts profitability. Sprouts Farmers Market (NASDAQ: SFM), meanwhile, is opening stores at a record pace even as sales at existing locations lose momentum.
Both stocks trade below their historical valuation ranges. But the discounts are telling two different stories.
MZTI looks like a value-and-margin recovery bet.
SFM looks more like a store-expansion growth story facing a near-term productivity test.
The distinction matters because cheap stocks don’t always offer the same margin of safety.
MZTI’s New Growth Engine Is Bachan’s
Marzetti generated about $1.93 billion in fiscal 2026 net sales, with revenue split roughly 52% from Retail and 48% from Foodservice.
The portfolio spans sauces, dressings, dips, croutons and frozen breads, while the Foodservice operation supplies major restaurant customers.
But the investment case is increasingly centered on one business: Bachan’s.
MZTI acquired the Japanese barbecue-sauce brand on May 1, 2026, and the early contribution has been meaningful.
In just two months of consolidation, Bachan’s added roughly $15.4 million in sales, contributed about 640 basis points to fourth-quarter Retail sales growth, and added roughly 520 basis points to Retail volume growth.
Scanner sales were still growing 8.7%, while total distribution points increased by more than 16%.
That suggests the opportunity isn’t simply accounting-driven.
Bachan’s is still expanding its shelf presence.
And MZTI now has a larger distribution, manufacturing and procurement platform that could help accelerate that expansion.
The company plans to launch Bachan’s Japanese Mayonnaise and Wing Sauce in fiscal 2027, while shifting some production into its Horse Cave facility.
That gives management several levers at once:
distribution growth, new products, in-house production and procurement savings.
The Bigger Story Is Margin Expansion
Bachan’s matters not only because it is growing, but because it carries higher margins than much of MZTI’s existing portfolio.
Management expects fiscal 2027 adjusted sales to grow at a mid-single-digit rate and adjusted gross margin to expand by about 100 basis points.
Roughly half of that margin improvement is expected to come from Bachan’s, with the other half coming from productivity, procurement and commodity-management initiatives.
That is an important detail.
MZTI isn’t simply hoping commodity prices fall.
The company already has a margin-improvement track record.
In the fiscal fourth quarter, gross profit rose 7.4%, reported gross margin increased 220 basis points and adjusted gross margin improved 160 basis points.
Adjusted operating income rose 17.5%.
All of that came even as reported sales declined 2.2%.
The quarter marked the 12th consecutive quarter of year-over-year gross-margin improvement.
That makes MZTI’s current setup unusual: sales growth is weak, but earnings quality is improving.
The Risk: Bachan’s Is Doing a Lot of the Work
The problem is that the legacy business isn’t yet healthy enough to call this a clean turnaround.
Fourth-quarter sales fell 2.2% to about $465 million.
Adjusted sales, excluding the impact of a temporary supply agreement, rose just 0.4%.
More importantly, core volume and product mix excluding Bachan’s were a roughly 330-basis-point drag.
During the earnings call, analysts estimated organic Retail volume excluding Bachan’s fell about 7%.
That creates the central tension in the MZTI thesis.
Management is guiding to mid-single-digit sales growth for fiscal 2027.
But much of that growth could come from Bachan’s, while the underlying Retail business is expected to decline modestly.
So the real question isn’t whether MZTI grows revenue.
It is whether Bachan’s becomes a new growth layer on top of a stabilizing core business—or merely hides continued weakness in legacy brands.
That distinction will matter far more than the headline growth rate.
Fiscal 2027 Starts With a Soft Patch
Investors also shouldn’t expect a clean first quarter.
Dressings remain a weak spot, and Cyclospora-related disruption is expected to reduce fiscal first-quarter revenue growth by about 250 basis points.
Management expects first-quarter sales to be roughly flat, gross margin to show little improvement and operating income to fall about 15%.
That makes the second half of fiscal 2027 more important than the first.
Investors will want to see whether dressing demand normalizes and whether Bachan’s can continue to expand quickly enough to offset weakness elsewhere.
Commodity inflation adds another variable.
Soybean oil prices have risen sharply, creating pressure for a company heavily exposed to sauces and dressings.
MZTI expects moderate inflation in fiscal 2027 and plans to offset it with pricing and productivity.
But with core volumes already weak, aggressive price increases carry their own risk.
Higher prices can protect margins while hurting demand.
MZTI’s Valuation Is Where the Setup Gets Interesting
MZTI trades at about 14.5 times earnings.
That isn’t the cheapest multiple among food peers, but it is dramatically below the company’s own five-year average of about 31.5 times.
Its price-to-sales ratio of roughly 1.4 times compares with a five-year average near 2.6 times.
Its price-to-book ratio of about 2.6 times is also well below a historical average of roughly 5.1 times.
The stock therefore looks far cheaper relative to its own valuation history than it does relative to every peer.
A discounted-cash-flow estimate puts fair value around $152.92 a share, compared with a market price near $101.34.
That implies roughly 51% upside to the DCF estimate.
Investors are also being paid to wait.
Based on annual dividends of about $4.15 a share, MZTI offers a yield of roughly 4.1% at the current price.
That gives the stock three potential return drivers:
earnings growth, multiple expansion and dividend income.
SFM’s Growth Story Is Much Cleaner—At First Glance
Sprouts Farmers Market is pursuing a completely different strategy.
Its growth engine isn’t acquisitions.
It is store openings.
SFM ended the second quarter with 490 stores across 25 states.
The development pipeline includes more than 110 executed leases and 155 approved locations.
Management now expects 42 net new stores in fiscal 2026, including 43 openings and one closure.
At least 15 stores are expected to open in the third quarter alone, the fastest quarterly opening pace in company history.
That gives SFM a highly visible growth runway.
Even with weak comparable-store sales, total fiscal 2026 revenue is still expected to increase 5.5% to 6.5%.
New stores are also performing well across markets such as California, Florida and New York.
As long as unit economics remain attractive, SFM can keep growing through a simple formula:
more stores → more revenue → more scale.
That is the strongest part of the SFM story.
Private Label and E-Commerce Add Another Layer
SFM also has internal growth levers that could improve economics over time.
Sprouts Brand now accounts for about 26% of sales and is growing faster than the company overall.
Private label can improve differentiation, customer loyalty and margin control.
If private-label penetration keeps rising, SFM could improve the quality of its sales mix.
E-commerce is also becoming more important.
Digital sales rose more than 12% in the second quarter and now account for roughly 16% of total sales.
Management says many digital shoppers remain active in stores as well, making them valuable omnichannel customers rather than purely online shoppers.
SFM is also increasing self-distribution across categories including fresh meat and selected private-label products.
That gives the company more control over freshness, shrink, service levels and potentially margins.
Those are real long-term strengths.
The problem is that they aren’t yet showing up clearly in near-term profit growth.
Existing Stores Are the Weak Point
Comparable-store sales fell 1% in the second quarter.
Full-year guidance calls for comps ranging from a decline of 0.5% to growth of just 0.5%.
That means almost all of SFM’s current sales growth is being generated by new locations.
That can work for a long time if new-store returns remain strong.
But the model becomes less attractive if store count keeps rising while existing-store productivity keeps falling.
That is the risk investors need to watch.
The company is also seeing more price sensitivity among consumers as grocery inflation and fuel volatility pressure household budgets.
SFM has responded with promotions, affordability initiatives, pricing investments and loyalty programs.
Management says the results have been mixed.
That creates a trade-off.
More promotions could help traffic, but at the cost of gross margin.
 Surya Rianto
Revenue Is Growing Faster Than Profit
The second-quarter numbers show the issue clearly.
Sales rose 4.7%.
But operating income fell from $179.4 million to $174.2 million.
Net income declined from $133.7 million to $129.2 million.
Gross margin slipped to 38.7%, down 12 basis points from a year earlier.
SG&A also deleveraged by about 30 basis points.
Put simply:
SFM is generating more revenue, but not more operating profit.
That is the most important near-term weakness in the story.
The third quarter may remain difficult.
Management expects comparable sales between negative 0.5% and positive 1.5%, with EBIT margin down about 50 basis points year over year.
The drivers include fixed-cost deleverage, heavy store-opening activity, fuel costs and some Cyclospora-related pressure.
SFM still has a credible long-term growth story.
But near-term execution needs to improve before that growth translates into stronger profitability.
SFM Is Cheap, but the Discount Is Smaller
SFM trades at roughly 13.6 times earnings, below its five-year average of about 19.4 times.
Its current P/E is also lower than peers such as OLLI, TGT, KR and ACI.
That makes the stock look inexpensive on earnings.
The discount is less dramatic on other measures.
Price-to-sales is around 0.8 times, only slightly below its five-year average of about 0.9 times.
A DCF estimate of roughly $81.64 a share sits only about 11% above a market price near $73.46.
That is a much thinner valuation cushion than MZTI currently offers.
SFM also pays no dividend, meaning shareholder returns rely more heavily on earnings growth, buybacks and share-price appreciation.
Two Cheap Stocks, but Only One Has a Wide Margin of Safety
The contrast between the two companies is becoming fairly clear.
SFM has the cleaner structural-growth story.
It has a visible store pipeline, strong new-store performance, growing private-label penetration and a meaningful e-commerce business.
If comparable sales recover while the company continues opening 40 or more stores a year, SFM could regain operating leverage and produce attractive long-term earnings growth.
But the current valuation already reflects much of that potential.
With the stock only about 11% below the DCF estimate used here, the margin for execution mistakes is relatively limited.
MZTI carries more operating uncertainty.
Its legacy Retail business is weak, dressings are under pressure and Bachan’s is responsible for much of the current growth story.
But the valuation discount is far larger.
The stock trades well below its historical P/E, price-to-sales and price-to-book multiples.
Its DCF estimate suggests roughly 51% upside from the current price, and investors receive a dividend yield near 4.1% while waiting.
That creates a more asymmetric setup.
For MZTI, the key question is whether Bachan’s can become a genuine second growth engine while the legacy portfolio stabilizes.
For SFM, the key question is whether rapid store expansion can continue without persistent deterioration in comparable-store sales and margins.
At current prices, MZTI offers the stronger valuation cushion and the broader set of potential return drivers.
SFM offers the more visible expansion runway.
But until existing-store productivity improves, investors are being asked to pay closer to fair value for a business whose revenue growth is not yet translating into profit growth.
MZTI is riskier operationally.
It may also be the stock where the market is leaving more room for something to go right.
The numbers are only the beginning.
Every week, Mikirduit US breaks down earnings, valuations, catalysts, and risks across U.S. stocks—so you can see what the market may be missing.
Mikirduit US provides independent financial research and educational content. This article is not personalized investment advice, and investors should conduct their own research before making investment decisions.