IonQ, D-Wave or Rigetti? Three Quantum Stocks, Three Very Different Paths to the Future
IonQ, D-Wave and Rigetti are taking very different paths toward commercial quantum computing. Here is how their technologies, revenue models and risks compare.
Mikirduit — Quantum-computing stocks have fallen out of favor, even as investors continue to look toward 2029 and 2030 as a potential inflection period for the industry. That raises a more practical question: among today’s pure-play quantum names, which business models and technologies look the most compelling?
3 Key Takeaways
- IonQ has the strongest scale today, with the largest revenue base and about $485 million in RPO, but its trapped-ion architecture still faces scaling and gate-speed challenges.
- D-Wave stands out for commercial usage today, with QCaaS contributing roughly 60% of quarterly revenue and a clearer optimization-focused product-market fit.
- Rigetti offers the highest hardware optionality, with fast superconducting gates and growing system sales, but it still has to prove fidelity, scaling and repeatable demand.
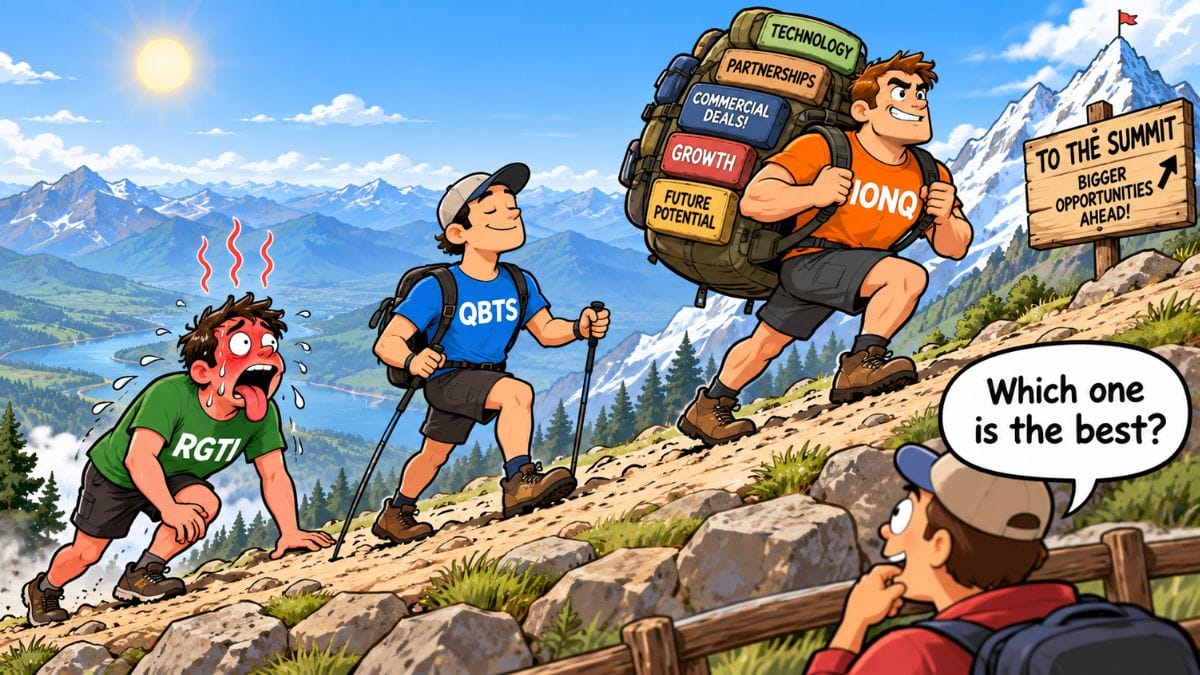
Three publicly traded companies stand out as relatively pure plays on quantum computing: Rigetti Computing (NASDAQ: RGTI), D-Wave Quantum (NASDAQ: QBTS), and IonQ (NYSE: IONQ). Each is taking a different technological path, and each is building a very different business around it.
Quantum computers are not simply faster versions of classical computers. Classical machines use bits that represent either a 0 or a 1. Quantum computers use qubits, which can be thought of as behaving more like a spinning coin: before measurement, the state can reflect a combination of possibilities rather than a fixed 0 or 1. That allows quantum systems to process certain classes of problems in ways that are fundamentally different from classical machines.
The potential applications are broad. Quantum systems could eventually help with drug discovery, materials science, logistics and factory scheduling, portfolio optimization, and cybersecurity. But one point is critical: qubit count alone does not determine system quality. A machine with 10,000 unreliable qubits could be less useful than one with 1,000 high-quality qubits if error rates are too high.
That is what makes IonQ, D-Wave and Rigetti so interesting. They are not merely competing on qubit counts. They are competing on architecture, fidelity, scalability and, increasingly, commercialization.
IonQ: The Broadest Platform, but Scaling Remains the Test
IonQ currently has the largest revenue base of the three companies. Its business is built around quantum-system deployments, cloud access, development services, and a broader portfolio spanning quantum networking, sensing, security and space-related businesses, some of which came through acquisitions.
Among IonQ’s customers are the Korea Institute of Science and Technology Information, or KISTI, in South Korea and QuantumBasel in Switzerland. The basic model is straightforward: a customer orders a quantum system, IonQ builds it, ships components, installs the system and brings it into operation. Revenue is then recognized over time as contractual obligations are fulfilled.
Through the second quarter of 2026, IonQ reported a GAAP net loss of about $1.87 billion, although most of that figure came from roughly $1.65 billion in warrant-liability effects tied to movements in IonQ’s share price. In other words, the accounting loss significantly overstated the underlying operating loss. Revenue, meanwhile, rose 287% to $80.1 million, and management guided for full-year 2026 revenue of $280 million to $290 million.
IonQ also reported $485 million in remaining performance obligations, or RPO, representing contracted revenue that has not yet been recognized because products or services have not been fully delivered.
The technological challenge is different. IonQ uses trapped-ion systems, which are known for high accuracy but can face slower gate speeds than superconducting systems because operations rely on precisely manipulating ions, traditionally with lasers. Scaling is also difficult: adding more ions while maintaining precise control becomes increasingly complex.
IonQ is trying to address part of that scaling problem through semiconductor manufacturing. The company acquired SkyWater Technology for about $1.8 billion, giving it more control over manufacturing and parts of its supply chain.
There is also an interesting strategic hedge in that deal. If another quantum architecture ultimately proves superior, SkyWater could still provide manufacturing services or components to the broader quantum industry. In that sense, IonQ is trying to build not just a quantum-computer business, but infrastructure around the sector itself.
 Surya Rianto
D-Wave: The Most Commercially Proven Use Case
D-Wave’s revenue model is more service-oriented.
The company has three main revenue sources.
The first is Quantum Computing as a Service, or QCaaS, through its Leap cloud platform. Customers do not need to buy their own quantum machine; they can rent access to D-Wave’s annealing systems through the cloud. QCaaS accounted for roughly 60% of quarterly revenue.
The second is professional services, where D-Wave helps customers identify and build quantum-computing use cases. A manufacturer with dozens of factories, hundreds of warehouses and thousands of delivery routes, for example, might use D-Wave’s team to formulate and optimize that problem using quantum computing. Professional services contributed about 30% of revenue.
The third is physical quantum-system sales to governments, national laboratories, research institutions and other strategic customers. Revenue from those sales depends on the stage of installation and project completion.
Through the first half of 2026, D-Wave’s net loss improved to roughly $66.4 million from $172.8 million a year earlier. Revenue, however, fell 67% to $5.9 million from $18.1 million.
The drop was mainly a timing issue tied to system sales. Recognized system revenue fell about 97% to $341,000, as fewer installation milestones were recognized during the period.
D-Wave ended June with about $40.7 million in RPO, and management expects roughly 57%, or about $23 million, to be recognized within the following 12 months.
D-Wave’s biggest advantage is that its annealing technology is already being used commercially today. Annealing is designed for optimization problems rather than general-purpose quantum computing, which makes it more practical for real-world use cases such as logistics and scheduling. That gives D-Wave a clearer product-market fit today than many pure gate-model approaches.
The trade-off is that annealing cannot run every type of quantum algorithm. To broaden its technological scope, D-Wave acquired Quantum Circuits for about $550 million, adding a gate-model effort based on superconducting hardware and software.
That gives D-Wave two potential paths: monetize annealing now, while retaining upside if its gate-model roadmap succeeds later.
Rigetti: A More Concentrated Hardware Bet
Rigetti generates revenue from three main sources:
- sales of quantum computers and components, which contributed about 79.8% of quarterly revenue;
- collaborative research and professional services, at about 18.5%;
- access to quantum-computing systems, at about 1.7%.
That makes Rigetti, at least for now, more of a hardware and R&D contractor than a cloud-usage business.
The company can develop superconducting quantum processors to customer specifications and sell quantum systems or quantum processing units, or QPUs, directly.
In the first half of 2026, Rigetti posted a net loss of about $19.5 million, while revenue rose 191% to $9.54 million. Its disclosed RPO stood at only about $2.7 million, with roughly $1.6 million expected to be recognized within 12 months.
Rigetti also has a letter of intent with the U.S. Department of Commerce for as much as $100 million in potential funding over three years to support research and development in superconducting quantum computing.
The technological appeal of Rigetti is clear. Its superconducting gates operate much faster than IonQ’s trapped-ion approach, and its manufacturing pathway more closely resembles conventional semiconductor fabrication, which could offer a clearer route toward mass production if the architecture scales. Rigetti is also pursuing a pure gate-based model, meaning the potential addressable market could be much broader if the technology reaches useful scale.
The downside is equally clear. Rigetti must solve fidelity and scaling at the same time. Superconducting qubits are more error-prone than trapped ions, and error management becomes increasingly difficult as qubit counts rise. They also require extreme cooling, leaving a narrow window for computation before errors accumulate.
So Which Quantum Stock Has the Most Interesting Position?
Quantum computing is still in an early development stage. None of these companies has reached mass adoption, and the industry remains open enough that all three could still carve out meaningful positions.
IonQ is the largest of the three by revenue and contracted backlog, but its technology is not immune to being overtaken. D-Wave could develop into a scaled quantum-services platform, particularly if QCaaS becomes the preferred way for enterprises to access quantum computing. Rigetti remains the more concentrated technology bet: if its superconducting architecture works at scale, the upside could be significant. If its full-system strategy struggles, its QPUs and components could still become valuable within a more modular quantum ecosystem.
One complication is that D-Wave also manufactures QPUs, so Rigetti would not have the component market to itself.
For now, valuation remains difficult across the sector. These companies are still refining both their technology and their business models, while variable costs, commercialization timelines and technical milestones remain highly uncertain. That makes traditional valuation frameworks less useful than they would be for a mature semiconductor or software company.
The numbers are only the beginning.
Every week, Mikirduit US breaks down earnings, valuations, catalysts, and risks across U.S. stocks—so you can see what the market may be missing.
Mikirduit US provides independent financial research and educational content. This article is not personalized investment advice, and investors should conduct their own research before making investment decisions.