Meta Eyes Nearly $100 Billion in Stock Sales to Fund Its AI Push. Is the Dip Worth Buying?
Meta Platforms is reportedly planning to raise close to $100 billion in stock sales to fuel its AI expansion, just as its free cash flow turns negative and shares slide nearly 19%. Here is what the plan means, how the stock is valued, and what investors should watch next.
Mikirduit – Meta Platforms (NASDAQ: META) is reportedly planning one of the largest equity raises in tech history. Shares have already slid sharply. Here is what investors should know.
Key Takeaways
- A massive equity raise is reportedly on the way. Meta plans to raise nearly $100 billion in the first quarter of 2027, combining a $35 billion common and preferred share offering with an at-the-market program of up to $60 billion in non-voting Class C shares, all to fund AI infrastructure.
- Strong earnings, weakening cash flow. Third-quarter revenue rose 28.8% to $181.71 billion and net income climbed 39.2%, but free cash flow turned negative at $2.12 billion, and nine-month free cash flow is down 62.6% as AI spending surges.
- The stock looks cheaper, but caution is warranted. Shares fell 18.86% in two weeks and now trade below their five-year average valuations (21.1x P/E versus 24x). Still, near-term technical pressure and the risk of a Fed rate hike make this look more like a short-term trade than a long-term bet.
Meta Platforms is reportedly preparing to raise close to $100 billion through stock offerings in the first quarter of 2027. The money would help pay for the company’s aggressive expansion in artificial intelligence. The news comes as interest rates remain elevated and the stock has already taken a beating.
What Meta Is Planning
The plan reportedly has two parts.
1. A $37.5 billion offering of common and preferred shares.
This portion is meant to support Meta’s AI investments. Nvidia (NASDAQ: NVDA), Advanced Micro Devices (NASDAQ: AMD) and Broadcom (NASDAQ: AVGO) are said to be interested in taking part, with a combined commitment of about $5 billion.
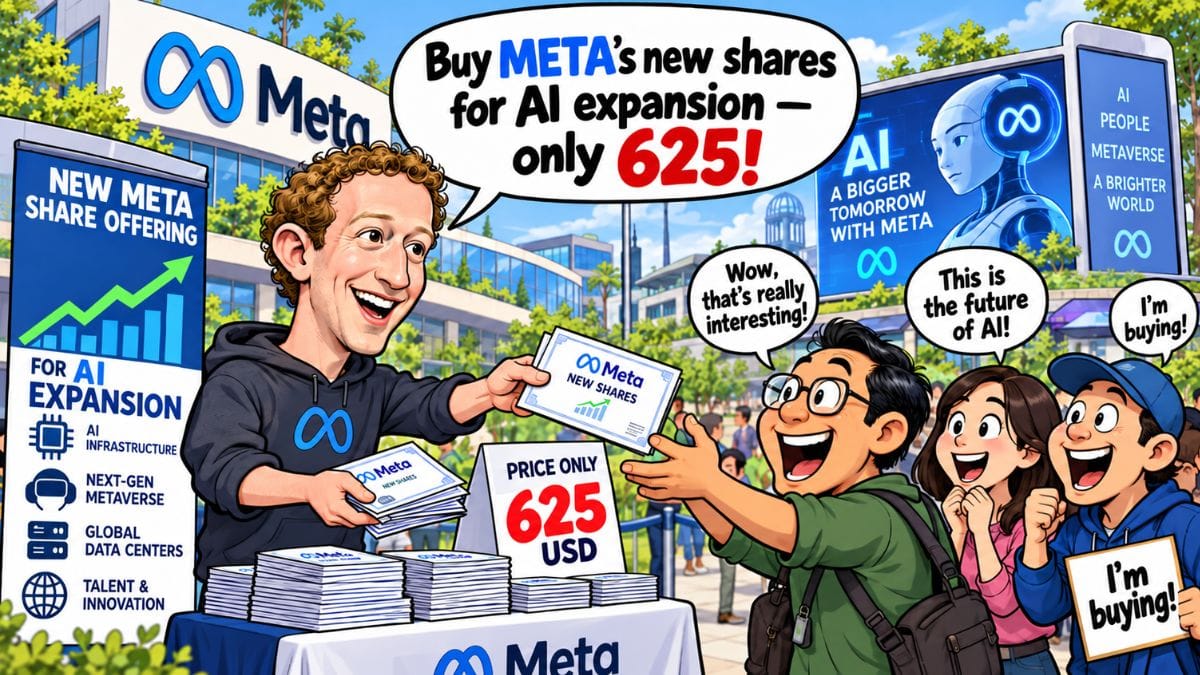
Under the structure described, Meta would issue $25 billion of common stock at $625 per share. It would also issue $12.5 billion of convertible preferred stock carrying a 6.5% annual dividend. That adds up to $37.5 billion in gross proceeds before fees.
2. An at-the-market program of up to $60 billion.
Meta also plans to launch an at-the-market (ATM) offering of non-voting Class C shares in the first quarter of 2027. In an ATM program, a company sells new shares gradually on the open market rather than all at once. Proceeds would go toward AI infrastructure and what Meta calls “personal superintelligence.”
Meta says its AI spending is already paying off, pointing to higher user engagement and improvements in advertising and monetization. The company has also said it expects 2026 capital expenditures of $135 billion to $145 billion.
How Meta Is Performing
Through the third quarter of 2026, Meta’s results look solid on the surface. Net income rose 39.2% to $52.48 billion, and revenue climbed 28.8% to $181.71 billion.
Operating income tells a more complicated story. It fell 6.7% to $54.64 billion, mainly because of $9.89 billion in legal expenses. Excluding that one-time item, operating income would still be growing.
Meta says AI is lifting several parts of the business, though it does not break out AI revenue separately:
- Facebook and Instagram: AI-powered recommendations are increasing the time users spend on the apps.
- Advertising: Improved AI models have raised conversion rates by up to 9.6% in some campaign categories.
- WhatsApp and small businesses: Paid messaging and subscriptions helped drive 59% growth in the “Family of Apps Other” segment.
- Muse AI agent: More than 10 million users have completed setup. Revenue still comes from subscriptions.
- Enterprise AI: This includes APIs, Muse Code and Business Agents. No separate revenue figures have been shared.
- Reality Labs: AI glasses sales are growing, but not enough to offset weaker Quest sales.
- Internal operations: Software output per engineer has more than doubled.
The Cash Flow Problem
The biggest worry for investors, and a key reason the stock fell after earnings, is cash flow.
Meta reported negative free cash flow of $2.12 billion in the third quarter. Free cash flow for the first nine months of 2026 was still positive at $11.05 billion, but that is down 62.6% from a year earlier.
The cause is heavy AI spending on data centers, AI servers, added computing capacity and new AI products.
 Surya Rianto
Is This a Repeat of Meta Spark?
Meta has walked away from a big bet before. It launched Meta Spark Studio, its augmented reality platform, on April 18, 2017. The company funded it internally, and the total spending was never disclosed. Meta announced it would shut the project down on August 27, 2024, and made it official in January 2025. The stated reason was a shift of resources and computing power from augmented reality toward AI.
Could the AI push end the same way? Probably not, at least not in the same sense. Unlike Spark, AI is already contributing to Meta’s growth, even if the gains are hard to isolate.
The real risk is profitability. The costs are enormous, and the more likely outcome is not a failed project but a slower, more limited expansion if costs keep rising and the economy cools as interest rates climb.
Is the Stock Cheap Now?
Meta shares have dropped 18.86% between October 13 and October 27, 2026. Is that enough to make them attractive?
Compared with Alphabet (NASDAQ: GOOGL) and Amazon (NASDAQ: AMZN), Amazon looks cheaper on price-to-earnings. On EV/EBITDA, however, Meta is the cheapest of the three.
Meta is also trading below its own five-year averages:
| Metric | Meta today | 5-year average |
|---|---|---|
| Price-to-earnings | 21.1x | 24x |
| EV/EBITDA | 13.6x | 15.1x |
What to Watch Next
The Federal Reserve announces its latest policy decision on October 28, 2026. If rates are held steady, that could give markets some relief heading into the November inflation report.
Technical signals still point to near-term pressure, though. Selling volume has been rising. The stock is also now trading below the $625 per-share price in the planned stock offering.
For investors considering a position, one approach is to wait for a short-term bounce before buying. This looks like a trading opportunity rather than a long-term bet. There is a real risk to the broader US market if the Fed raises rates by 50 basis points by the end of 2026.
Mikirduit US provides independent financial research and educational content. This article is not personalized investment advice, and investors should conduct their own research before making investment decisions.